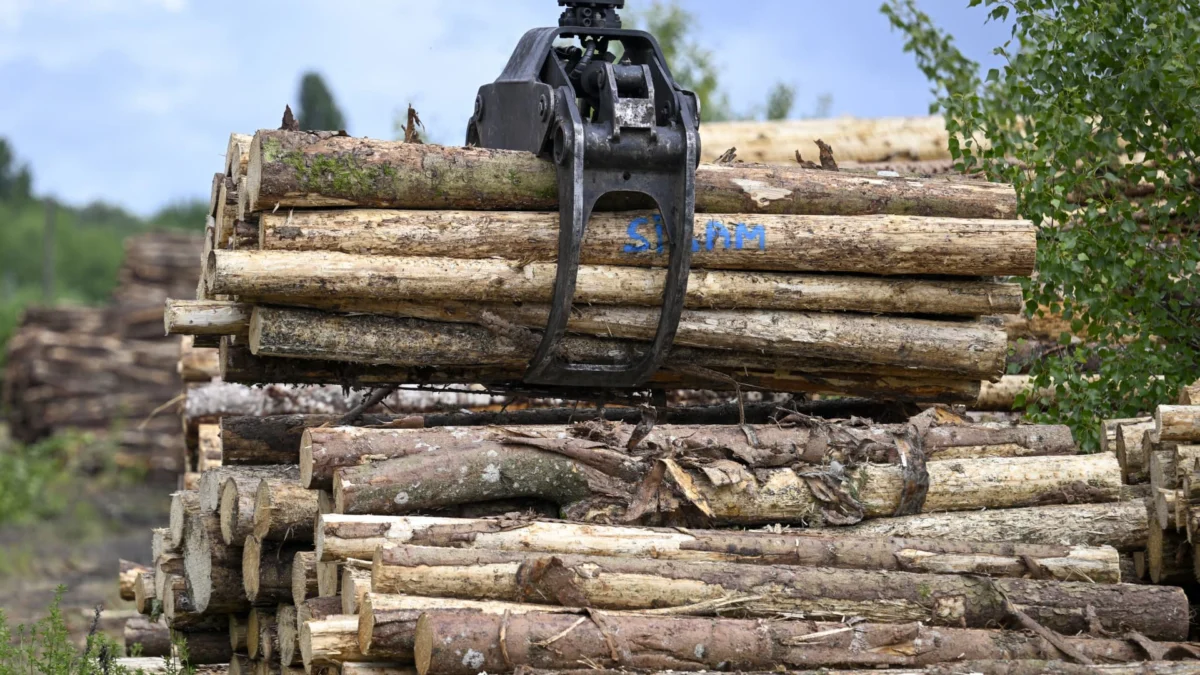
Investors are buying up vast tracts of timberland across the U.S. Timberland managers acting for pension funds and other institutional investors can wait decades for returns, but the market can also be a profit trap, according to US Top News and Analysis.
This surge in timberland investing reflects a search for alternative assets that may hedge against inflation and provide steady long-term returns, though such purchases carry risks when returns fail to materialize as expected.
Key Facts
- Investors are purchasing large U.S. timberland tracts.
- Timberland managers buy on behalf of pension funds and institutional investors.
- Returns may take decades to realize.
- The market can become a profit trap.
The Story
Who is affected by this shift?
Pension funds, endowments, and other institutional investors are increasingly allocating capital to timberland investing as they seek diversified long-term holdings. These entities typically rely on specialized timberland managers to acquire and oversee timberland assets, since the asset class demands expertise in forest management, harvest cycles, and commodity markets.
For rural communities and landowners, these purchases can reshape local economies. Timberland managers often consolidate fragmented private holdings into larger plantations, which may alter traditional land use patterns and affect generations-old family forests.
What happens next for timberland investors?
Timberland investing rewards a patient, long-term approach. Trees may take 25 to 35 years to reach harvestable maturity, meaning pension funds and institutional investors must wait decades before realizing returns on their capital. During that time, managers must balance ecological sustainability, regulatory compliance, and fluctuating lumber prices.
However, timberland investing is not without risk. Market downturns, disease outbreaks, wildfires, or shifting construction demand can reduce timber values or delay harvests. If returns fall short of projections, investors may find themselves trapped in underperforming assets, turning what looked like a stable long-term bet into a profit trap.
How did we get here?
The rise of timberland investing has been driven by institutional investors seeking stable returns uncorrelated with traditional stocks and bonds. Over the past decades, pension funds and insurers have expanded into alternative assets, including infrastructure and natural resources.
Timberland offers unique characteristics: biological growth continues regardless of market conditions, and well-managed forests can appreciate while sequestering carbon. Yet the illiquid nature of these assets and their sensitivity to environmental and economic shocks mean timberland investing requires deep expertise and a tolerance for long lock-up periods.
What We Know — and What We Don’t
Verified by the source:
- Investors are buying vast tracts of timberland across the U.S.
- Timberland managers act for pension funds and institutional investors.
- Returns may require waiting decades.
- The market can also function as a profit trap.
Still unconfirmed:
- Total dollar amount of recent timberland acquisitions.
- Specific geographic regions leading the buying trend.
- Names of individual pension funds or timberland managers involved.
- Historical return rates or performance data for these investments.
Why It Matters
Timberland investing represents a significant allocation of institutional capital into natural resources, influencing rural land markets and long-term financial planning for retirement systems. Understanding the risks and time horizons helps readers see how everyday investments like pension funds connect to forests, construction, and global commodity demand.
What to Watch
Future developments in lumber markets, climate policy, and forest management practices will shape whether timberland investing delivers the long-term returns investors expect.
Meta description: Investors are buying vast U.S. timberland tracts, but timberland investing may be a profit trap despite long-term appeal.
Read more about market trends in our economy and markets coverage.