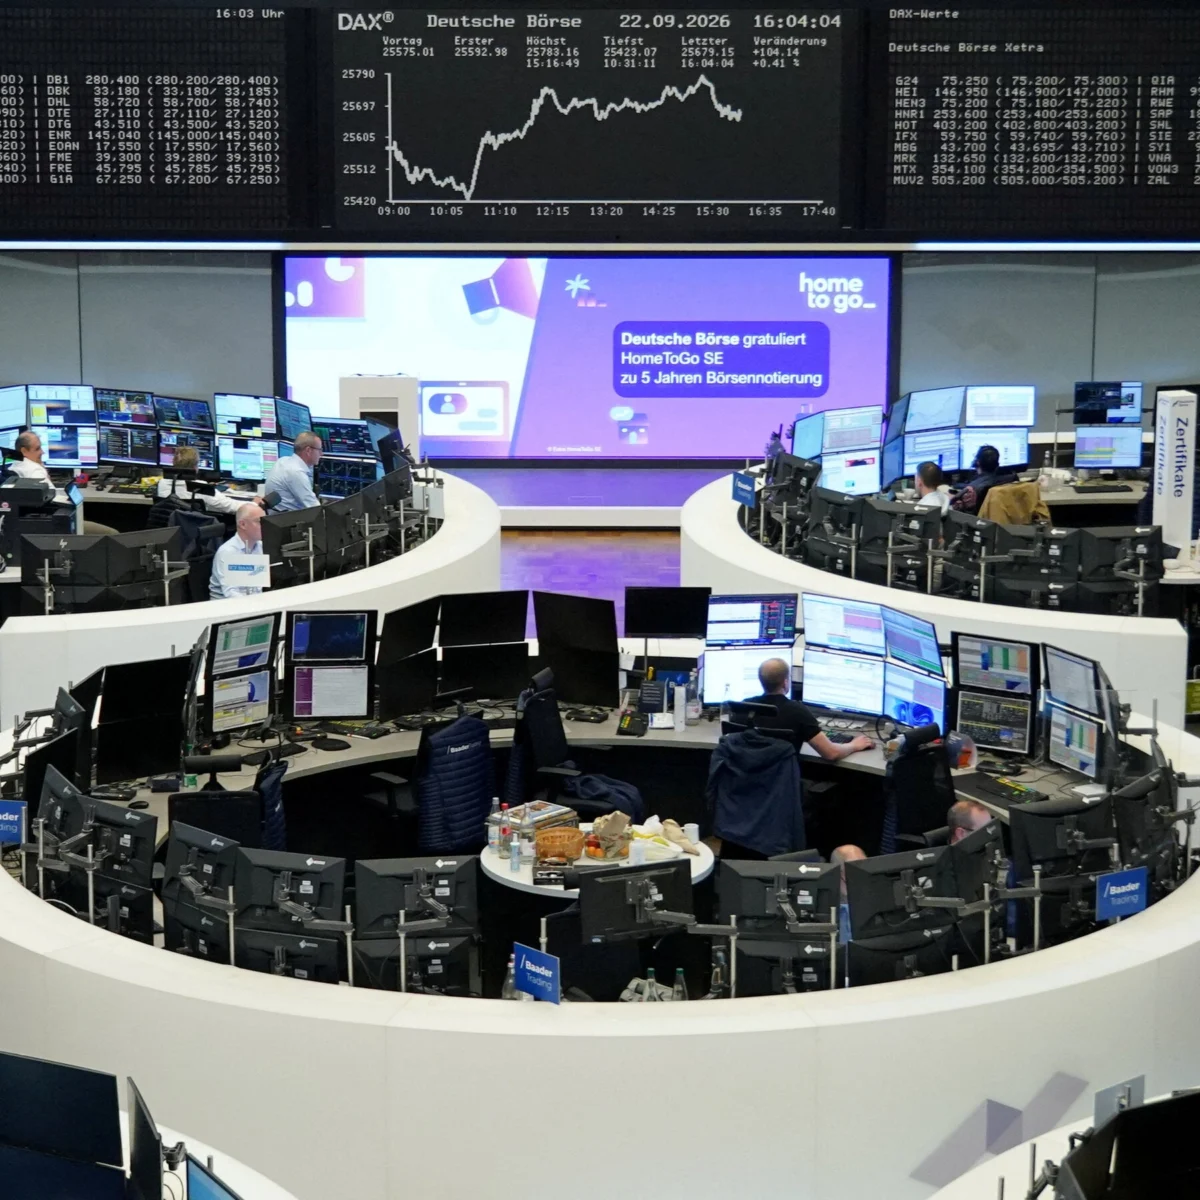
Bond markets remained volatile Tuesday while oil prices continued climbing, extending momentum from a sharp government debt sell-off the previous day. The movement reflects ongoing investor adjustments to shifting economic signals, with energy markets responding to supply-demand tensions and fixed-income trading reacting to changing rate expectations.
The rise in crude benchmarks coincided with renewed volatility across sovereign debt markets, where yields fluctuated as traders weighed conflicting data on inflation, employment, and central bank policy. Analysts note such cross-asset moves often signal transitional periods in which traditional safe-haven assets temporarily lose ground to riskier counterparts.
Key Facts
- Bond markets experienced renewed volatility.
- Oil prices rose for the session.
- The climb followed a sharp sell-off in government debt the prior day.
- Market participants reacted to evolving economic indicators.
What Drove the Cross-Market Movement?
The interplay between rising oil prices and bond market jitters illustrates how interconnected modern financial systems have become. When crude gains traction, inflationary pressures can prompt expectations of tighter monetary policy, which in turn unsettles debt holders. Conversely, when bonds wobble, investors may rotate toward commodities perceived as stores of value. This dynamic played out visibly across global exchanges, where energy futures advanced alongside Treasury yield swings.
Such behavior is not unusual during transition phases, particularly when macroeconomic reports paint mixed pictures about growth trajectories. Traders frequently recalibrate positions based on new data points—employment figures, consumer price indices, or geopolitical developments—all of which were active drivers in recent sessions.
While no single catalyst dominated headlines, cumulative effects amplified reactions across sectors. For instance, a slight uptick in payroll numbers could reinforce bets on prolonged high rates, indirectly boosting dollar-denominated commodities like oil. Similarly, soft retail sales might encourage buying in longer-duration bonds, temporarily stabilizing yields after earlier turbulence.
How Did We Get Here?
Market participants entered the week digesting last session’s abrupt shift in government bond valuations—a move interpreted broadly as a repricing of future rate paths. That sell-off set off ripple effects, pushing equities lower at the open before paring losses, while simultaneously lifting crude prices through momentum-driven flows.
Since then, investors have parsed central bank commentary for hints about trajectory changes. With little concrete guidance emerging yet, markets continue oscillating between fear and optimism, reflected clearly in today’s mixed performance across asset classes.
Analysts emphasize that these gyrations do not necessarily presage broader instability but rather reflect adaptive recalibrations within fluid macro conditions. Still, sharp intraday swings warrant caution among retail traders who may lack sophisticated hedging tools used by institutional desks.
Meta description: Oil prices rise and bond markets stay volatile after government debt sell-off, reflecting shifting investor sentiment around rate outlook.
What We Know — and What We Don’
Verified by the source:
- Bond market volatility increased.
- Oil prices climbed during the trading session.
- A prior-day sell-off occurred in government debt markets.
Still unconfirmed:
- Exact magnitude of yield changes.
- Specific drivers behind individual commodity moves.
- Official commentary from policymakers.
- Long-term implications for portfolio allocations.
Why It Matters
Fluctuations in bond markets and commodity pricing affect savings vehicles, pension fund returns, and borrowing costs across economies. When investors react strongly to modest shifts in economic data, it underscores uncertainty surrounding long-term financial planning—for both individuals and institutions navigating volatile times ahead.
What To Watch
Markets will likely remain sensitive to incoming economic reports, especially those touching inflation trends and labor market health. Any deviation from consensus projections risks amplifying existing tensions already evident in oil and bond interactions observed today.